With interest rates remaining high, what does a typical investment property need to look like to eventually become cashflow positive?
Let’s look at a real-world example using a house currently listed in Frankston South, VIC:
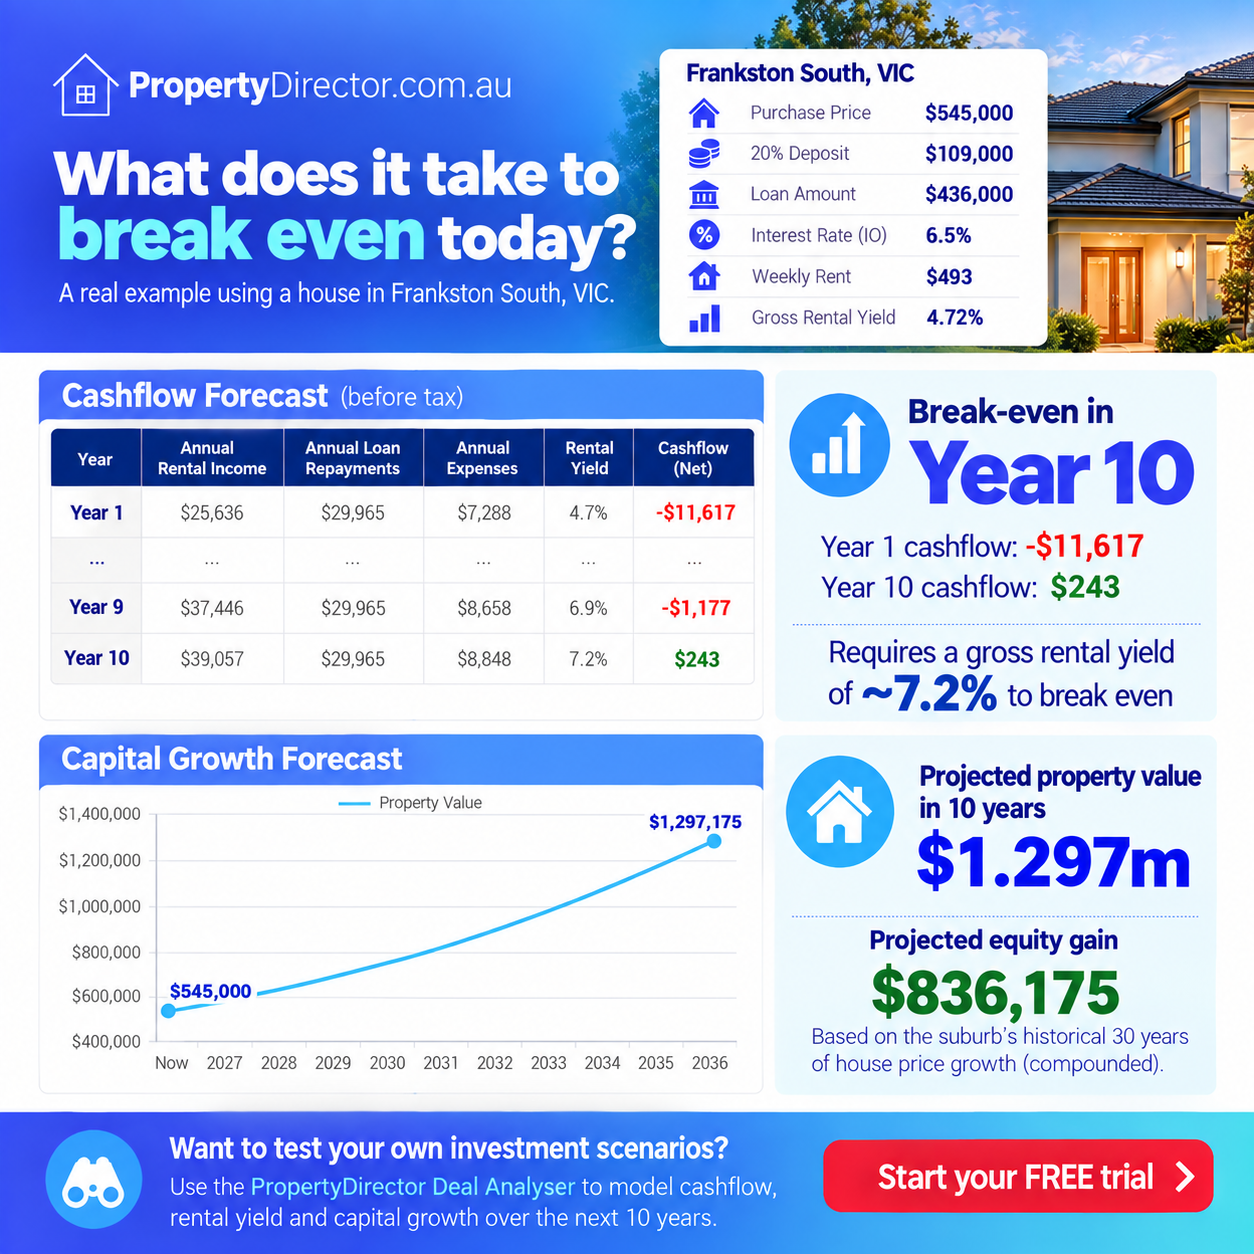
* Purchase Price: $545,000
* 20% Deposit: $109,000
* Loan: $436,000
* Interest Rate: 7% interest-only
* Weekly Rent: $493
* Gross Rental Yield: 4.72%
Using typical property outgoings and allowing for annual increases in rent and expenses, the PropertyDirector Deal Analyser projects a Year 1 negative cashflow of $11,617 before tax.
Based on these assumptions, the property doesn’t reach cashflow break-even until Year 10, when it generates a small positive cashflow of $243. By that point, the gross rental yield has increased to approximately 7.2%.
But cashflow is only one part of the investment picture.
Based on PropertyDirector’s projection using the suburb’s historical 30-year house price growth rate, the property value could increase from $545,000 to approximately $1.27 million over 10 years, producing projected equity of around $836,175.
This highlights an important consideration for investors: a property can remain negatively geared for many years while potentially building substantial equity through capital growth.
Want to test a property before you buy?
Register for a free PropertyDirector trial at www.propertydirector.com.au/free-trial and use the Deal Analyser to model cashflow, rental yield and capital growth over the next 10 years.